
Short Answer
Overview
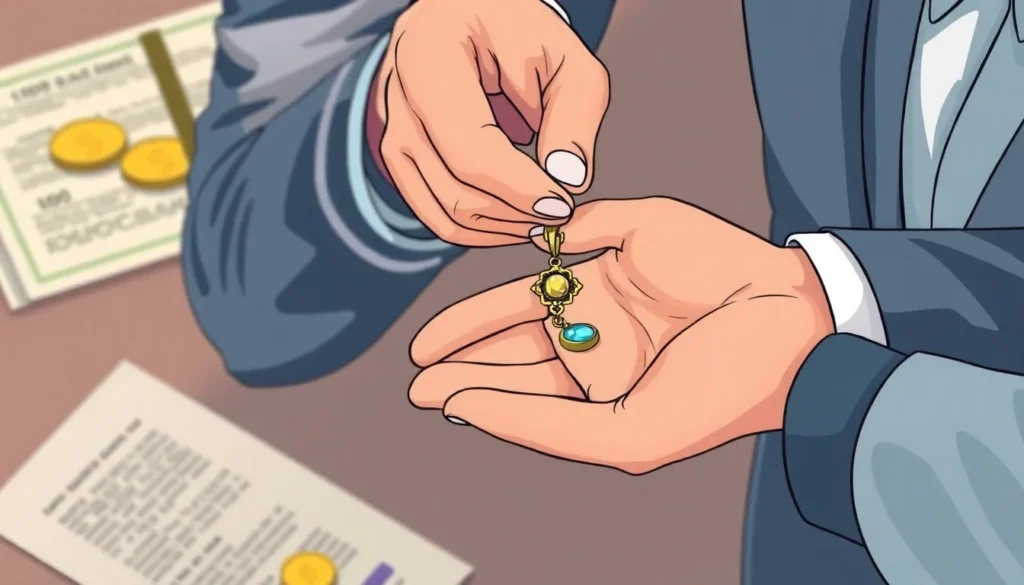
A pledge loan is a form of secured credit in which the borrower offers movable property as collateral to the lender. Unlike mortgages that involve immovable property, pledge loans typically involve tangible personal property such as valuables, stocks, or commodities. The borrower retains ownership of the pledged asset but temporarily transfers possession to the lender or a third party until the loan is repaid. This arrangement provides security for the lender against the risk of default.
Detailed Explanation
In a pledge loan, the asset pledged serves as a guarantee that the borrower will fulfill their repayment obligations. The key characteristic is that the pledged asset is movable and tangible, differentiating it from other secured loans like mortgages or liens on real estate. The lender holds possession of the collateral during the loan term, which acts as a form of security interest. If the borrower fails to repay the loan, the lender has the legal right to sell or otherwise dispose of the pledged asset to recover the outstanding debt.
The types of assets used as collateral in pledge loans vary widely and may include jewelry, stocks, bonds, warehouse receipts, agricultural products, or machinery. The valuation of the pledged collateral is typically assessed before the loan is issued to determine the loan amount relative to the asset’s market value.
How It Works
The process of obtaining a pledge loan generally involves several steps:
- Asset Selection: The borrower identifies an eligible movable asset to pledge.
- Valuation: The lender or an appointed expert appraises the asset’s market value.
- Agreement: The borrower and lender enter into a contractual agreement outlining loan terms, collateral details, repayment schedule, interest rate, and rights upon default.
- Possession Transfer: The borrower physically delivers the pledged asset to the lender or a custodian, who takes possession while ownership remains with the borrower.
- Loan Disbursement: Upon successful transfer and agreement, the lender releases the loan amount to the borrower.
- Repayment and Release: The borrower repays the loan as agreed, and upon full repayment, the pledged asset is returned.
- Default Handling: If the borrower defaults, the lender may enforce their rights to sell the asset and recover the loan amount.
Examples
- Jewelry Pledge Loan: A borrower pledges valuable jewelry to a pawnshop or financial institution as collateral for a short-term loan.
- Stock Pledge Loan: An investor pledges shares of stock as security for a loan from a bank or brokerage.
- Warehouse Receipt Loan: A farmer pledges stored grain or agricultural produce represented by a warehouse receipt to obtain financing.
Pros and Cons
- Pros: Provides access to credit without selling assets; typically offers lower interest rates than unsecured loans due to reduced lender risk; flexible use of various movable assets as collateral; faster approval compared to some secured loans.
- Cons: Risk of losing the pledged asset in case of default; possession transfer may limit borrower’s use of the asset; valuation disputes can arise; typically short-term loans with possibly higher costs for longer terms.
Comparison Table
| Aspect | Pledge Loan | Mortgage Loan |
|---|---|---|
| Meaning | A loan secured by movable property with possession transferred to the lender. | A loan secured by immovable property, such as real estate, with a lien on the property. |
| Collateral Type | Movable assets (jewelry, stocks, commodities). | Immovable assets (land, buildings). |
| Possession | Transferred to lender or custodian during loan term. | Borrower retains possession; lender holds lien. |
| Loan Term | Usually short to medium term. | Typically long term. |
| Risk to Borrower | Loss of pledged asset upon default. | Possible foreclosure of property upon default. |
Decision Checklist
- Use this if: You have valuable movable assets that you can temporarily hand over as collateral and need relatively quick access to funds.
- Avoid this if: You cannot afford to lose the pledged asset or need to keep possession of it during the loan term.
- Check this first: The valuation of your asset, loan terms, interest rates, and legal rights upon default to ensure the loan fits your financial situation.
What is the easiest way to understand a Pledge Loan?
Think of a pledge loan as borrowing money by handing over a valuable item to the lender temporarily. You keep ownership but give possession as security. If you repay the loan, you get your item back; if not, the lender can sell it to recover the money.
FAQ
What assets can be used for a pledge loan?
Movable tangible assets such as jewelry, stocks, bonds, warehouse receipts, and commodities can be used as collateral for a pledge loan.
Does the borrower lose ownership of the pledged asset?
No, the borrower retains ownership, but possession of the asset is transferred to the lender or custodian until the loan is fully repaid.
What happens if the borrower defaults on a pledge loan?
If the borrower defaults, the lender has the right to sell the pledged asset to recover the outstanding loan amount.
Leave a Reply